1. Is It Illegal to Give Someone Your Bank Account in Taiwan?
Providing another person with a bank account number is not necessarily illegal. The legal risk arises when the arrangement amounts to delivering or providing an account for another person's independent use without a legally recognized reason.
Article 22 of Taiwan's Money Laundering Control Act regulates this conduct to prevent financial accounts from being used to conceal criminal proceeds, facilitate fraudulent transactions, or circumvent customer identification requirements.
1.1 What Does Article 22 of the Money Laundering Control Act Prohibit?
Article 22, Paragraph 1 prohibits individuals from delivering or providing certain financial accounts or payment accounts for another person's use unless a statutory exception applies. The provision covers accounts opened in the individual's own name or another person's name. It also recognizes that legitimate commercial transactions, financial practices, and relationships of trust may require some form of authorized account use.
The law therefore does not prohibit every instance of account sharing. Its focus is on arrangements in which another person obtains control over an account without a legitimate justification. For example, providing an account number so a customer can pay an invoice is materially different from allowing an unknown person to operate the account independently.
➙Whether the conduct violates Article 22 depends on the actual circumstances rather than the mere fact that financial information was disclosed.
1.2 Which Financial and Virtual Asset Accounts Are Covered?
Article 22 applies to several categories of accounts, including accounts opened with financial institutions, accounts maintained with virtual asset service providers, and accounts established with third-party payment service providers.
Traditional bank accounts, relevant cryptocurrency or virtual asset accounts, and regulated third-party payment accounts may therefore fall within the provision. The account does not necessarily have to belong to the person who transfers it. Providing another person's account for unauthorized use may also raise legal concerns.
💡The essential question remains whether the conduct constitutes an unlawful delivery or provision of account control.
2. What Does Transferring Account Control Mean?
The concept of account control is central to understanding Article 22. The legislative explanation underlying the provision identifies delivery or provision for another person's use with transferring control of the account to that person.
This interpretation distinguishes ordinary financial communication from conduct that enables another individual to use an account as an independent financial instrument.
2.1 The Legal Meaning of Account Control
Account control generally concerns the practical ability to operate an account and determine how it is used. Relevant indicators may include possession of an ATM card, knowledge of withdrawal or transfer passwords, access to online banking credentials, control over verification codes, and the authority to initiate transactions.
For example, if a person gives another individual the ATM card, password, and online banking credentials needed to transfer funds without further authorization, that arrangement may indicate a transfer of control. By contrast, where the account holder retains the ability to authorize transactions and the recipient cannot independently operate the account, the legal analysis may be different. Control must be assessed substantively. Physical possession of a bank card or knowledge of a password is relevant evidence, but the complete arrangement and actual transaction authority must also be considered.
2.2 Sharing an Account Number Versus Giving Someone Access
An account number primarily identifies where money can be transferred. It does not ordinarily allow another person to withdraw funds or initiate payments. For that reason, merely providing an account number to receive a legitimate payment generally does not amount to transferring control under Article 22. A different situation arises when the account holder provides credentials or other means allowing another person to conduct transactions independently.
Nevertheless, the presence of account credentials does not automatically establish an unlawful transfer in every case. The legislative explanation also recognizes situations in which an account holder temporarily entrusts another person with an ATM card and password to withdraw money on the account holder's behalf. Where the transaction remains part of the account holder's own financial activity, the arrangement may differ from transferring the account for another person's independent use.
➙The purpose of the transaction, the identity of the person making decisions, and the actual control over funds are therefore more important than any single item of account information.
3. When Does Providing a Bank Account Become a Criminal Offense?
Article 22 establishes different legal consequences depending on the circumstances of the account provision. An unlawful transfer may lead to an administrative police warning, while specified aggravating circumstances can trigger criminal liability.
It is important to distinguish these consequences because not every violation of Article 22 automatically results in imprisonment.
3.1 Criminal Penalties for Providing Three or More Accounts
Under Article 22, Paragraph 3, Subparagraph 2, a person who unlawfully delivers or provides a total of three or more covered accounts may face criminal punishment. The statutory penalty is imprisonment for up to three years, short-term imprisonment, or a fine of up to NT$1 million, with fines potentially imposed together with imprisonment.
The provision refers to the combined number of covered accounts or account identifiers. The relevant accounts may include those maintained with financial institutions, virtual asset service providers, or third-party payment providers.
However, the prosecution must establish an unlawful delivery or provision under Paragraph 1. Simply identifying three account numbers that were disclosed to another person does not, by itself, establish that control over three accounts was transferred. Whether the accounts were provided as part of one relevant course of conduct, whether the statutory exceptions apply, and what authority the recipient actually obtained may all require examination.
3.2 Paid Account Transfers and Repeat Violations
Providing three or more accounts is not the only circumstance that may trigger criminal liability. Article 22, Paragraph 3 also addresses unlawful account provision involving agreed or received compensation, as well as qualifying repeat violations within five years after a police warning.
For example, receiving payment in exchange for allowing another person to operate a bank account may create criminal exposure even where fewer than three accounts are involved. Similarly, a person who has already received a qualifying police warning and commits another violation within the statutory five-year period may face criminal consequences. These circumstances must be distinguished from ordinary authorized transactions or legitimate reimbursements.
🧑🏻⚖️The existence of compensation, a prior warning, or multiple accounts does not eliminate the need to establish the underlying unlawful conduct.
3.3 Police Warnings and Banking Restrictions
Under Article 22, Paragraph 2, a person who unlawfully provides an account may receive an administrative warning issued by the competent municipal or county police authority. Article 22 also provides for restrictions involving financial institutions, virtual asset service providers, and third-party payment service providers. Depending on the applicable regulations, these measures may include suspending or limiting certain account functions, restricting financial services, or closing affected accounts.
A police warning is an administrative measure and should not be confused with a criminal conviction. Likewise, a flagged bank account associated with a criminal investigation is not necessarily the same as an administrative warning under Article 22.
⚠️Individuals who receive a police warning should identify the issuing authority, the stated legal basis, and the available administrative remedies promptly.
4. How Have Taiwanese Courts Interpreted Account Control?
Judicial interpretation provides important guidance on the meaning of unlawful account provision. Courts have considered the legislative purpose of Article 22 and its predecessor provision, former Article 15-2, when distinguishing the disclosure of financial information from the transfer of account control.
4.1 Judicial Interpretation of Article 22
Taiwan Changhua District Court Criminal Judgment No. 68 of 2024 addressed the importance of control in determining whether the statutory requirements for unlawful account provision were satisfied.
The legal reasoning discussed in this context emphasizes that the prohibited conduct concerns delivering or providing an account for another person's use, rather than merely communicating identifying information. For the criminal offense involving three or more accounts, the prosecution must establish the relevant unlawful provision and the statutory account-number threshold. This distinction is particularly important when an accused person retained the ATM cards, passwords, online banking access, and practical authority to authorize transactions.
However, a defense based on retained control must be supported by the evidence. Courts may consider communication records, actual transactions, account access arrangements, and the conduct of everyone involved. A judicial interpretation from one case also does not guarantee the same result in another case involving different facts.
4.2 Three Examples of Bank Account Sharing
►Example 1: Providing an Account Number to Receive Money
A gives B a bank account number so B can transfer a payment. A retains the ATM card, password, online banking credentials, and exclusive authority to operate the account. B cannot independently withdraw money or initiate transactions from A's account.
In this situation, the disclosure of the account number generally does not amount to transferring account control for B's independent use.
►Example 2: Allowing Another Person to Operate Multiple Accounts
A gives B the ATM cards, passwords, and online banking access for three bank accounts. B can independently withdraw funds, transfer money, and conduct transactions without A's approval. If there is no legitimate reason for the arrangement, the conduct may constitute unlawful account provision.
Because three accounts are involved, criminal liability under Article 22, Paragraph 3, Subparagraph 2 may arise if the other statutory requirements are established.
►Example 3: Spouses Managing Household Finances
A and B are spouses who jointly manage household finances. Both have access to a bank account for family expenses and make transactions as part of their established financial arrangement. Where the arrangement genuinely arises from a family relationship of trust and serves a legitimate purpose, the statutory exception may apply.
The relationship alone is not conclusive, however. Courts and administrative authorities may still examine the actual purpose and use of the account.
5. What Are the Legal Exceptions to Article 22?
Article 22, Paragraph 1 expressly recognizes that some account-sharing arrangements have legitimate purposes. The statutory exceptions include ordinary commercial or financial practices, relationships of trust between family members or friends, and other legitimate reasons.
➙These exceptions prevent ordinary financial activities from being automatically treated as unlawful account transfers.
5.1 Ordinary Commercial and Financial Transactions
Certain business arrangements require authorized individuals to manage payments or conduct transactions on behalf of others.
For example, a company may authorize an employee to process payments through an account as part of established internal financial procedures. An individual may also provide account information to receive salary payments, refunds, business income, or repayment of a personal loan. Where the arrangement is consistent with legitimate commercial or financial practices, Article 22's exception may apply.
⚠️However, claiming that an account was provided for employment or a loan does not automatically establish a legitimate reason. A genuine employer or lender generally does not need unrestricted access to an applicant's ATM card, online banking password, or transaction verification credentials merely to pay wages or disburse a loan.
5.2 Trust Between Family Members and Friends
The law expressly recognizes account-sharing arrangements based on trust between family members or friends. For example, family members may authorize one another to manage household expenses, pay medical bills, or conduct transactions for an elderly relative.
Such arrangements may fall within the statutory exception when supported by a genuine relationship of trust and a legitimate financial purpose. Nevertheless, being related to someone does not automatically make every account transfer lawful. If the account is handed over for unrelated suspicious transactions, or the supposed relationship of trust is merely used to conceal an unlawful arrangement, the exception may not apply.
5.3 Other Legitimate Reasons
Article 22 also recognizes other legitimate reasons that may justify providing an account for another person's use. This open-ended exception allows authorities and courts to assess arrangements that do not fit neatly within ordinary commercial practices or family relationships.
Relevant considerations may include:
- the purpose of the arrangement
- the parties' relationship
- the scope of authorization
- the account holder's continuing involvement
- the actual transaction history
A legitimate reason should be supported by objective circumstances rather than a general assertion that the account was provided in good faith.
💡For example, a person who claims to have provided an account for a legitimate business purpose may need to produce contracts, transaction records, correspondence, or other supporting evidence.
6. How Can You Defend Against Illegal Account Provision Charges?
A defense under Article 22 should begin by identifying the exact conduct alleged by the prosecution or administrative authority. The central issues often include whether control was transferred, whether the recipient could independently operate the account, how many accounts were involved, and whether the arrangement had a legitimate purpose.
6.1 Evidence Showing You Retained Account Control
Evidence of actual control may be particularly important where the accused person only disclosed account information.
Relevant materials may include:
- bank statements
- transaction records
- ATM card possession records
- online banking access information
- communication histories
- documents showing who authorized particular payments
For example, if the accused person retained the banking credentials and personally approved every transaction, this may support an argument that another person never obtained independent control. Conversely, records showing that another person independently initiated withdrawals or transfers may support a different conclusion.
⚠️The evidence must be examined as a whole. Merely claiming that the account holder retained control may be insufficient if the transaction records suggest otherwise.
6.2 Distinguishing Account Provision from Fraud and Money Laundering
Unlawful account provision under Article 22 must be distinguished from aiding fraud and other money laundering offenses. Article 22 regulates certain account-transfer conduct even where the prosecution cannot establish all the elements of a separate fraud or money laundering offense. A charge involving aiding fraud or money laundering may require different findings concerning criminal conduct, knowledge, intent, and the defendant's contribution to the alleged offense.
Accordingly, an individual accused of providing a bank account should not assume that every related criminal allegation involves identical legal requirements. A defense lawyer may need to examine the elements of each alleged offense separately. This distinction is especially relevant where an individual provided financial information after being approached through a fake job offer, fraudulent loan advertisement, investment solicitation, or other deceptive communication.
➙The reason for providing the account, the information available to the accused person, and the actual extent of account control may all affect the legal analysis.
6.3 Practical Precautions for Account Holders
Individuals should exercise caution before allowing others to access bank accounts, cryptocurrency accounts, or third-party payment accounts.
- First, avoid providing ATM cards, passwords, online banking credentials, or transaction verification codes to unknown individuals without a clear and legitimate purpose.
- Second, where account access is genuinely necessary for family or business reasons, retain documents showing the purpose, scope of authorization, and identity of the person involved.
- Third, preserve relevant messages and financial records if an account becomes involved in suspicious transactions.
If police or prosecutors begin investigating an account, the account holder should clarify the nature of the allegation and obtain legal advice before making statements that may affect the defense. These precautions may help distinguish legitimate financial arrangements from unlawful transfers of account control.
7. How Can a Taiwan Money Laundering Defense Lawyer Help?
An allegation of unlawful account provision does not necessarily mean that the statutory requirements have been established.
Legal representation may focus on whether the accused person actually transferred control, whether the alleged conduct involved three or more accounts, whether compensation or a qualifying prior warning is involved, and whether a statutory exception applies. A lawyer may also review the evidence supporting related allegations of fraud or money laundering.
🧑🏻⚖️Chien Sheng International Law Firm provides legal services in criminal defense, fraud, money laundering, and financial account disputes in Taiwan, with offices in Taipei, Taoyuan, and Kaohsiung.
The firm's attorneys assist clients in reviewing account records, communication histories, transaction authorization, and the circumstances surrounding alleged account transfers. Where the evidence indicates that the accused person retained actual control, the defense may argue that the required element of unlawful delivery or provision was not established. Where control was transferred, the analysis may instead focus on the legitimate purpose of the arrangement, the defendant's individual conduct, and the applicable statutory provisions.
➙For individuals facing administrative police warnings, legal assistance may also involve reviewing the administrative decision and available appeal or revocation procedures. The appropriate strategy depends on the evidence and procedural status of the case.
8. Frequently Asked Questions (FAQ)
Q1. Is it illegal to give someone your bank account number in Taiwan?
Not necessarily. Merely providing an account number so another person can transfer money to you generally differs from giving that person independent control over the account. Article 22 focuses on unlawful account provision, subject to its statutory exceptions.
Q2. What does account control mean under Taiwan's Money Laundering Control Act?
Account control refers to the practical ability to operate an account and determine how it is used. Relevant evidence may include ATM cards, passwords, online banking credentials, transaction authorization, and the ability to withdraw or transfer funds independently.
Q3. Can I be prosecuted for providing three bank accounts?
Yes, potentially. Under Article 22, Paragraph 3, Subparagraph 2, unlawfully providing a total of three or more covered accounts may result in criminal liability. However, the prosecution must establish the unlawful provision and other statutory requirements.
Q4. What is the penalty for unlawfully providing three or more accounts?
The statutory penalty is imprisonment for up to three years, short-term imprisonment, or a fine of up to NT$1 million, with fines potentially imposed together with imprisonment.
Q5. Can providing only one bank account result in criminal punishment?
Yes, in certain circumstances. Article 22 also provides criminal penalties for qualifying account provision involving agreed or received compensation, or a repeat violation within five years after a relevant police warning. A single-account violation without these circumstances may instead lead to administrative consequences.
Q6. Can I let a family member use my bank account?
Potentially. Article 22 recognizes arrangements based on trust between family members or friends. Whether the exception applies depends on the genuine purpose of the arrangement and how the account is actually used.
Q7. Is providing my bank account for a job or loan application legal?
Providing an account number to receive wages or loan proceeds is generally different from surrendering control over the account. Giving an employer or lender unrestricted access to an ATM card, password, or online banking credentials may create serious legal risks and is not automatically justified by a job or loan application.
Q8. Does receiving a police warning mean I have been convicted of money laundering?
No. A police warning under Article 22 is an administrative measure, not a criminal conviction. However, it may have significant consequences for financial account services and may be relevant to qualifying future violations.
Q9. Can I defend myself by proving I never transferred account control?
Potentially. Evidence that you retained transaction authority and that another person could not independently operate the account may support a defense that the statutory requirement of delivery or provision was not satisfied. The outcome depends on the complete evidence.
Q10. What should I do if I am accused of illegally providing a bank account?
Preserve banking records, messages, transaction details, and evidence showing who controlled the account. Confirm whether the matter involves a police warning, an Article 22 criminal allegation, or separate fraud and money laundering charges. Seek legal advice promptly to assess the applicable requirements and defense options.
9. Conclusion
Providing a bank account number does not automatically constitute a crime under Taiwan's Money Laundering Control Act.
Article 22 primarily addresses the unlawful delivery or provision of financial accounts, virtual asset accounts, and third-party payment accounts for another person's use. The legal meaning of account control is therefore essential. An individual who merely discloses account information while retaining practical control may be in a materially different position from someone who allows another person to independently operate the account.
The law also recognizes legitimate exceptions involving ordinary commercial or financial practices, relationships of trust between family members or friends, and other justified arrangements. Where unlawful account provision is established, the consequences may include administrative police warnings, banking restrictions, and criminal penalties under specified circumstances, including providing three or more accounts, receiving compensation, or committing a qualifying repeat violation.
For defendants, the relevant evidence should be examined carefully to determine who actually controlled the account, why access was provided, and whether the statutory elements of each alleged offense have been satisfied.
🧑🏻⚖️Chien Sheng International Law Firm assists individuals facing allegations involving bank account transfers, money laundering, aiding fraud, and related criminal or administrative proceedings in Taiwan.Early evidence preservation and an accurate understanding of Article 22 may be essential to developing an appropriate legal defense.
【CHIEN SHENG LAW FIRM】
- LINE Online Legal Consultation::@lawuicc001(Click to Consult)
- Appointment by Phone::(03)⠀3150-034
- Payment Methods: Cash|Credit Card|Bank Transfer
【Learn More】
 【假投資詐騙與 eATM 試卡】人頭帳戶、車手、洗錢風險升高!刑事律師解析詐團金流漏洞與自保方法詐騙集團疑似利用 eATM 搭配讀卡機測試人頭帳戶金融卡,確認帳戶未遭警示後再安排車手提款。本文解析假投資詐騙如何結合投資群組、假平台、人頭帳戶、eATM 試卡與洗錢金流,並提醒被害人與被告應如何保存證據、報案及自保。詐欺案件知識文 2026.05.11
 Fraud and Money Laundering Asset Forfeiture in Taiwan: Taoyuan District Court Rulings on Courier Liability, Criminal Proceeds and ClawbackCan a fraud courier be forced to repay all the money collected from victims? Key Taoyuan District Court rulings explain how Taiwan courts should determine criminal proceeds, ownership, control, confiscation and clawback in fraud and money laundering cases.詐欺案件知識文 2026.08.31
 網路交友遇感情詐騙變詐欺車手怎麼辦?虛擬貨幣轉帳涉洗錢無罪辯護成功案例網路交友遇感情詐騙,幫對方收款換虛擬貨幣卻成詐欺被告?本文解析感情詐騙車手案件無罪辯護重點。詐欺案件知識文 2026.05.28
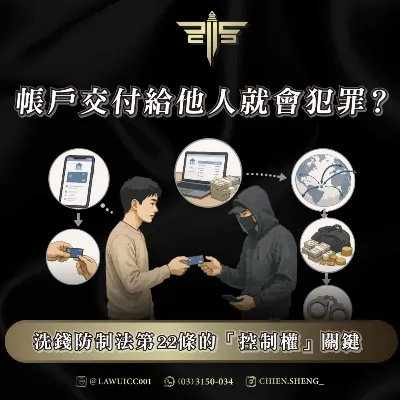 提供銀行帳戶就違反洗錢防制法嗎?第22條「控制權」、3個以上帳戶與正當理由完整解析只提供帳號,也可能涉及洗錢防制法第22條嗎?關鍵不只是有沒有交出提款卡或密碼,而是帳戶究竟在替誰處理金流、本人是否實質掌控,以及有沒有正當理由。一次看懂帳戶控制權、告誡與3個以上帳戶的刑責。詐欺案件知識文 2026.08.26